IRS Notice CP162
Your partnership or S corporation received a CP162, CP162A or CP162B notice with a penalty attached. Our CPAs check the IRS figures, fix the filing problem the IRS flagged and ask it to remove the penalty.
- 3000+ five star reviews
- Trusted in 27 countries
- All 50 States
The CP162B penalty and how to ask for removal
What it is. The IRS sends notice CP162 when it charges a penalty on a partnership or S corporation return; a CP162B is for an incomplete return or one not e-filed as required.
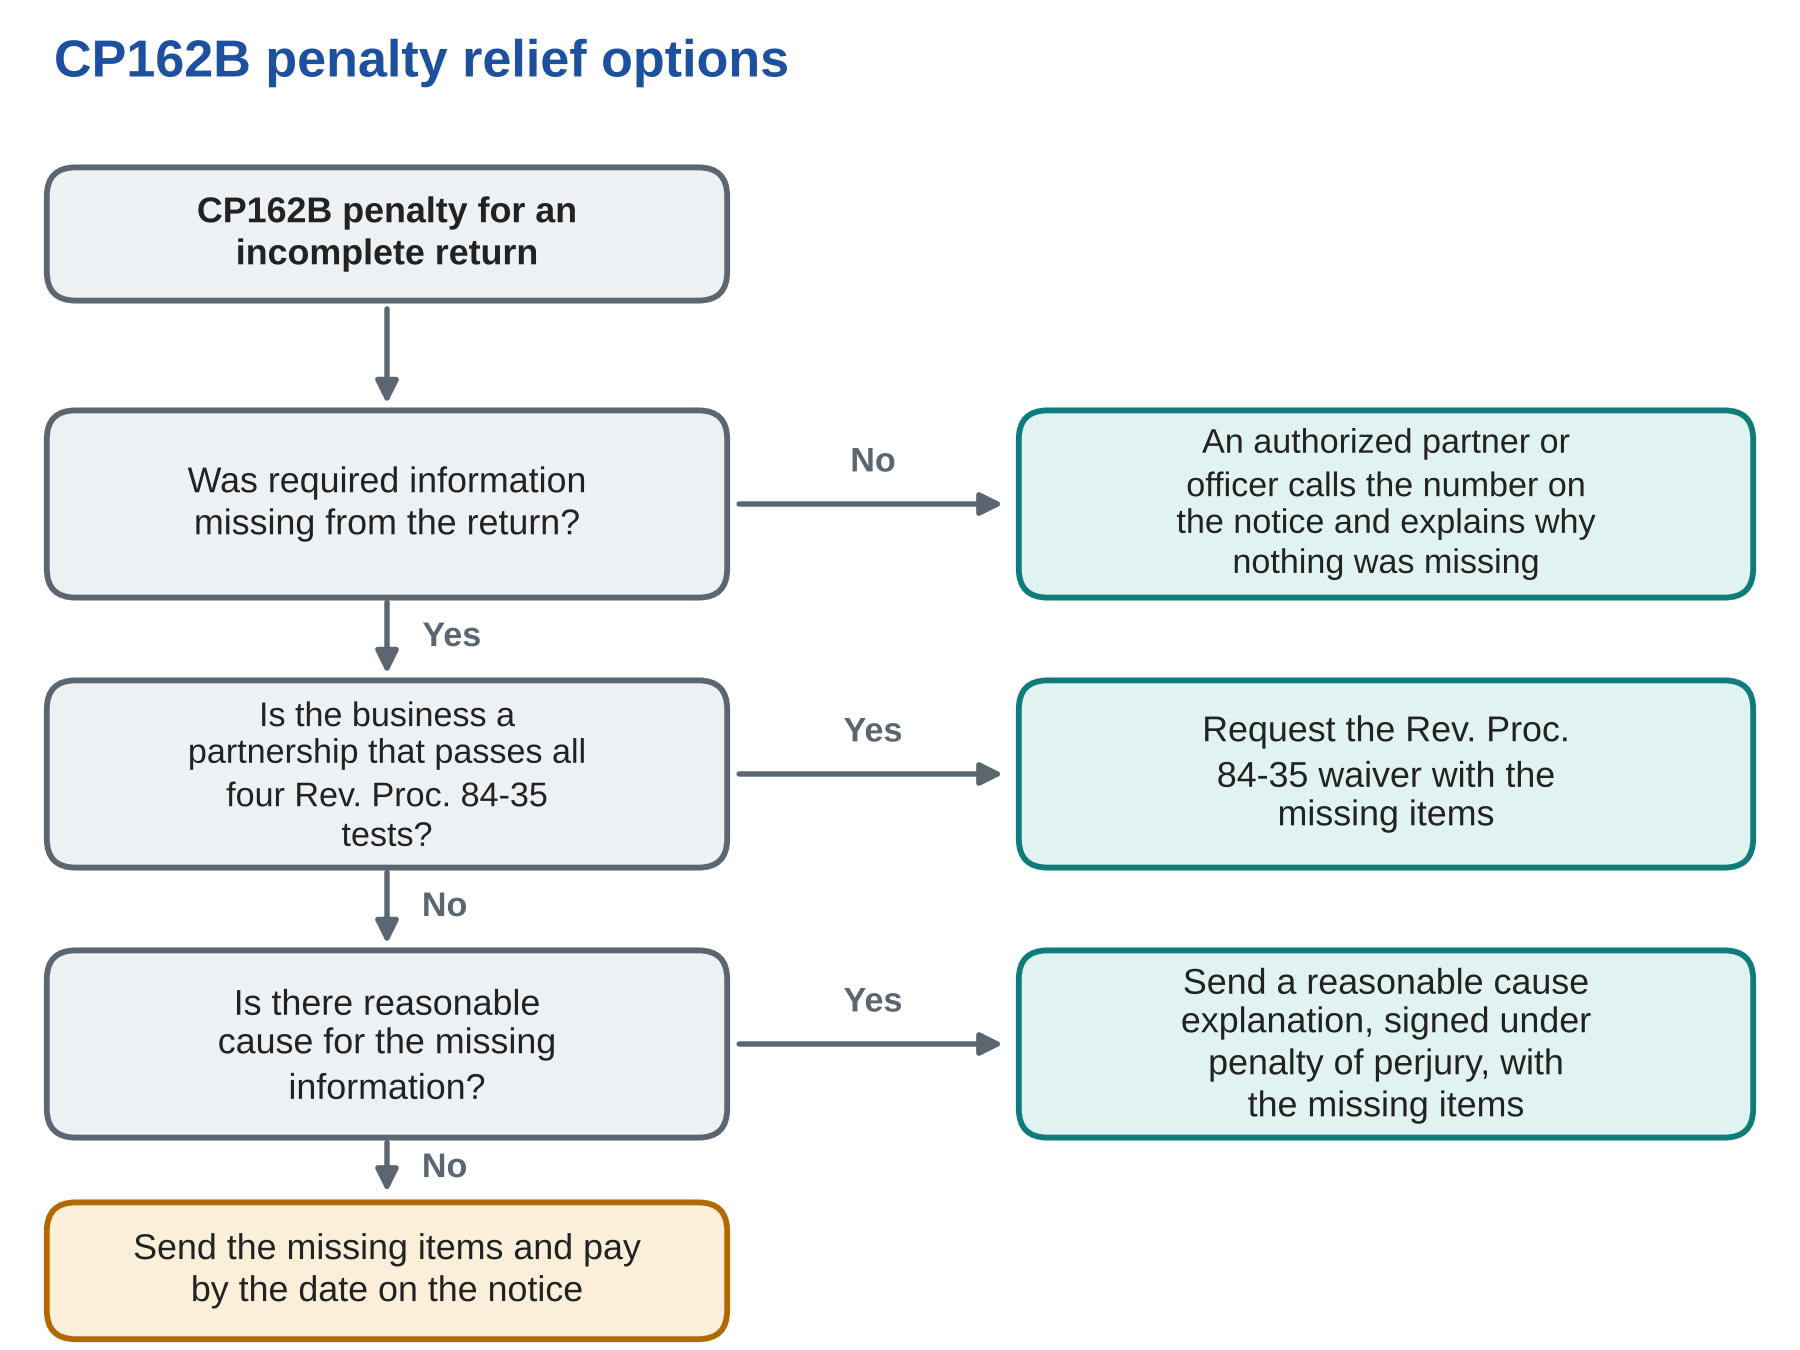
Relief options. Small partnerships that pass all four Revenue Procedure 84-35 tests can qualify for a waiver; other filers write to the IRS explaining why the information was missing.
How the penalty accrues. The IRS charges the CP162B penalty for each month or part of a month the information is missing, up to 12 months.
Notice CP162 vs CP162A vs CP162B
CP162.
The IRS charged the penalty because your business did not file its return electronically as required, per the CP162 notice page.
Partnerships with more than 100 partners must e-file Form 1065 (U.S. Return of Partnership Income). So must partnerships that file 10 or more returns of any type during the tax year, under the Form 1065 instructions.
The IRS can waive the rule for a partnership that requests a waiver in writing and shows that e-filing would cause a hardship.
CP162A.
The IRS charged the penalty for a late return, or for a return your business did not e-file as required, per the CP162A notice page.
If the business filed on time, an authorized partner or officer can call the IRS and fax proof, such as a timely extension or a mailing record.
CP162B.
The IRS charged the penalty for an incomplete return, or for a return your business did not e-file as required, per the CP162B notice page.
Required information means each item the IRS marks as required in the return instructions.
When a return is both late and incomplete, the IRS charges only for the missing information unless the return is at least 12 months late, under the Internal Revenue Manual.
CP162B penalty calculation
The IRS sets the penalty per partner or shareholder per month, adjusts it for inflation each year and prints the current figure in the Form 1065 and Form 1120-S instructions.
The IRS counts each person who was a partner or shareholder during any part of the tax year.
We use $255 in this example, the amount set in Revenue Procedure 2024-40.
A limited liability company (LLC) taxed as a partnership had four partners during the tax year and does not qualify for relief. The LLC filed its Form 1065 on time, including any extension, but left out required information. The IRS received the missing items in the fifth month after the due date:
| Calculation step | Amount |
|---|---|
| Penalty per partner, per month | $255 |
| Four partners | $255 × 4 = $1,020 a month |
| Five months, including the partial month | $1,020 × 5 = $5,100 |
| Cap for this penalty, before interest (12 months) | $1,020 × 12 = $12,240 |
Had the IRS received the items in the second month after the due date, the LLC would owe $1,020 × 2 = $2,040.
An S corporation that owes tax and files late also pays 5% of unpaid tax for each month or part of a month. The IRS caps that charge at 25% of the unpaid tax, per the Form 1120-S instructions.
How to respond to a CP162B notice
Work through the notice in this order:
Check the notice against the return.
Note the failure the IRS identifies, the tax year and the form. Then list the items missing from the return.
Call if the IRS made an error.
An authorized partner or officer can call the number on the notice. The caller explains why the information was not required, or why the business did not have to e-file, with proof such as a waiver.
Send the missing information.
Mail the items to the IRS office where the business filed the return.
Pay or ask for relief.
Pay by the date on the notice if you agree with the penalty. A pending relief request does not stop interest, which the IRS charges until the business pays in full, per the IRS penalties page. If the IRS removes the penalty, it removes the related interest too.
A partnership or S corporation can also authorize a CPA on Form 2848 (Power of Attorney and Declaration of Representative) to call the IRS about the notice.
Have a CPA handle your CP162B notice
Send us the notice and a copy of the return. A senior tax expert checks whether the IRS charged the right penalty.
With your authorization on Form 2848, we represent you before the IRS for the notice and tax year, send the missing information and ask for relief. You can also authorize us to receive copies of IRS notices. Everything you share stays confidential.
Revenue Procedure 84-35 for small partnerships
When a small domestic partnership files a late or incomplete return, the IRS presumes reasonable cause (an acceptable reason for the failure) if the partnership passes four tests.
The IRS sets the tests in Revenue Procedure 84-35 (Rev. Proc. 84-35):
10 or fewer partners. A husband and wife (and their estates) count together as one partner.
Individuals or estates only. Each partner is an individual (not a nonresident alien) or the estate of a deceased partner.
Pro rata shares. Each partner owns capital and profits in the same proportion, and the partnership allocates income, deductions and credits by those shares. Partners can hold different percentages.
Full reporting on time. Each partner fully reported their share of the partnership’s income, deductions and credits on a timely filed return.
The partnership has to ask for the waiver and provide facts showing how it meets each test. The IRS reassesses the penalty if it later finds a partner did not qualify or filed late.
A partnership that passes all four tests still has to file Form 1065 under the Form 1065 filing rules. The IRS waives only the penalty, per Chief Counsel Advice 201733013.
What to put in a Rev. Proc. 84-35 letter
Include the following in the waiver request:
Partnership and notice details.
The partnership’s name, employer identification number (EIN), tax year and the date on the CP162B notice.
The four tests.
One line per test, stating how the partnership meets it.
Each partner’s return.
Each partner’s name and filing date, with a statement that each partner fully reported their share of income, deductions and credits. Keep the proof, since the IRS can ask for it.
The request and signature.
A sentence asking the IRS to abate the penalty under Rev. Proc. 84-35, with the letter signed under penalty of perjury.
The missing information.
A copy of each item missing from the return, attached to the letter.
Mail the letter with the missing information. The IRS writes back to the partnership if it accepts the explanation.
First Time Abate vs reasonable cause
First Time Abate and automatic relief.
The IRS lists the penalty for a late partnership or S corporation return under First Time Abate (FTA), and leaves out the penalty for an incomplete one.
A business qualifies when it filed the same type of return on time for the three tax years before the penalty year. The business must also have no penalties in those years, apart from an estimated tax penalty or one the IRS removed for reasonable cause or error.
For newer original returns, the IRS applies Automatic Exemption from Penalty (AEP) in place of FTA and lists the tax years for each on its AEP page. With AEP, the IRS does not charge the penalty for a late return when the business filed and paid on time for the three prior years. The business does not need to request AEP.
For returns outside AEP, call the number on the notice to request relief; you do not need to name FTA.
Reasonable cause.
For a CP162B, the IRS can waive the penalty for reasonable cause after weighing the facts of the case.
Explain in writing what happened and when, why the business could not file a complete return, and what it did to comply.
Sign the explanation under penalty of perjury and send it with the missing information.
Great Customer Service. They answer Calls and Emails right away, even on weekends which I did not Expect. They were able to help me Re File my Corporate and Personal and remove Fines and interest.
 California Chiropractic Center, Google review.
Get help with next year’s business tax return
We prepare partnership and S corporation returns with each required schedule and e-file them by the due date. Send the notice and the return named on it, and a senior tax expert tells you what to fix before your next filing.
More help with business returns and IRS notices
- IRS audit representation. A CPA represents you in an IRS audit and handles the letters that follow.
- Corporate and partnership extensions.File Form 7004 (the extension request) and pay any tax by the due date, then file the complete return by the extended date.
- Business tax return preparation. Returns for S corporations, C corporations, partnerships and multi-member LLCs.

Reviewed by George Dimov, CPA. Certified to practice in all 50 states. 15+ years advising on individual and business tax. Last reviewed November 2026.