Get expert tax and accounting help!
Call (866) 681-2140

Missed depreciation for years?
Check what you can catch up.

No depreciation claimed? Wrong recovery period? A schedule you don’t trust? Get the history reviewed and find out whether Form 3115 can correct the shortfall.

01

Tell us what was claimed

Your schedule, property records and the years involved.

02

Know the route and the fee

Confirm the correction, calculations and cost before work begins.

03

Get the correction prepared

We rebuild the figures and prepare the agreed filing.

Over 3000 ★★★★★ Reviews

Start with the schedule.
Find the right correction.

Tell us when the property went into service and what was claimed. We’ll identify the records needed to review the route.

Have my schedule reviewed
The Dimov Tax team

Form 3115 depreciation catch-up.
The history behind the filing.

Form 3115 requests a change in accounting method. For a qualifying depreciation correction, Section 481(a) brings the prior difference into the year of change.

That can avoid reopening each prior return. But the right procedure depends on the error, the filing history and the applicable eligibility rules.

Dimov Tax reconstructs what you claimed and what was allowable, establishes the correction route and prepares the agreed form and supporting schedules.

Check which correction I need

Method change or amended return?

The type of error matters as much as the number of years. We establish the route before calculating the adjustment.

A depreciation method used over several years

An impermissible method used on two or more consecutive returns generally requires an accounting method change rather than simply amending those returns.

Claiming no depreciation can itself establish an impermissible method. The property and change must still meet the applicable procedure’s requirements.

Review my filing history

A single year or a different kind of error

A first-year issue, mathematical error or posting mistake may call for an amended return or another route. Some depreciation changes have special procedural rules.

Changes to basis, placed-in-service dates or elections are not automatically Form 3115 corrections.

Find out which route applies

IRS guidance on correcting depreciation

Years of differences.
One supported adjustment.

The Section 481(a) computation compares depreciation actually deducted with depreciation allowable before the year of change.

History

What was claimed

Reconstruct the filed deductions from the returns and schedules.

Recalculation

What was allowable

Apply the correct treatment to the substantiated depreciable basis.

Year of change

The cumulative difference

Calculate the applicable adjustment and connect it to the corrected schedule.

A negative adjustment generally reduces taxable income in the year of change.

A positive adjustment generally increases taxable income over four years, subject to exceptions.

A qualifying adjustment may include differences from older years without separately amending each return. That is different from a refund claim for an old year, and eligibility still needs a review.

Review my catch-up opportunity

What Form 3115 does not automatically fix.

A supported accounting method change has a specific job. It is not a substitute for missing evidence or a late election.

An election missed or revoked

Some elections require a separate procedure. Form 3115 does not by itself reinstate an election or reverse a valid election out of bonus depreciation.

Unsubstantiated costs

Purchase records, improvements and the land/building allocation support the calculation. We identify gaps before relying on the figures.

Property outside qualifying use

Ownership and the date eligible business or rental use began matter. No catch-up is created for property that did not qualify for depreciation.

From schedule review to the corrected return.

The reconstruction, Form 3115 and ongoing depreciation schedule stay connected.

01

Read the schedule

Review prior returns, depreciation schedules, purchase records and the date the property went into service.

02

Establish the route

Identify the error, applicant, year of change and applicable automatic or nonautomatic procedure. Agree the scope and fee.

03

Rebuild the figures

Recompute the depreciation history, calculate the adjustment and prepare Form 3115 where appropriate.

04

Implement the filing

Follow the required filing and duplicate-copy procedures where applicable, reflect the adjustment on the return and carry forward the corrected schedule.

Real people. The expertise behind your correction.

Our team includes CPAs, Enrolled Agents, tax accountants and financial planning specialists. The depreciation history is reviewed alongside your property ownership and tax return.

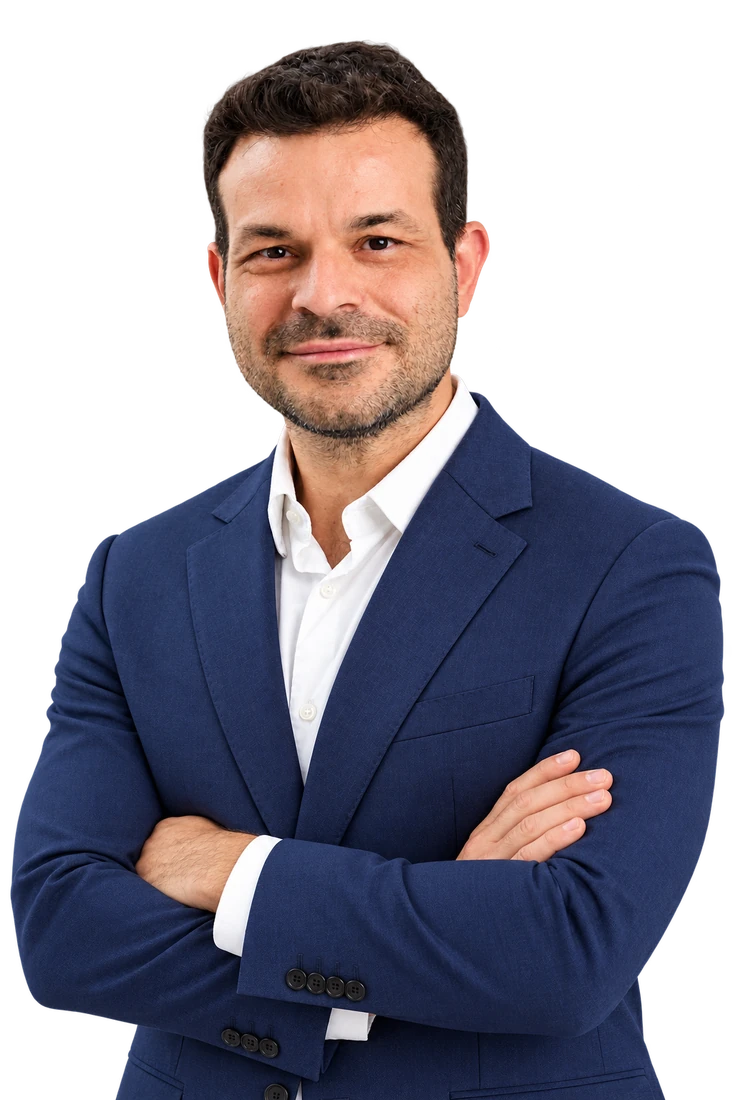
George Dimov

George Dimov

CPA · President

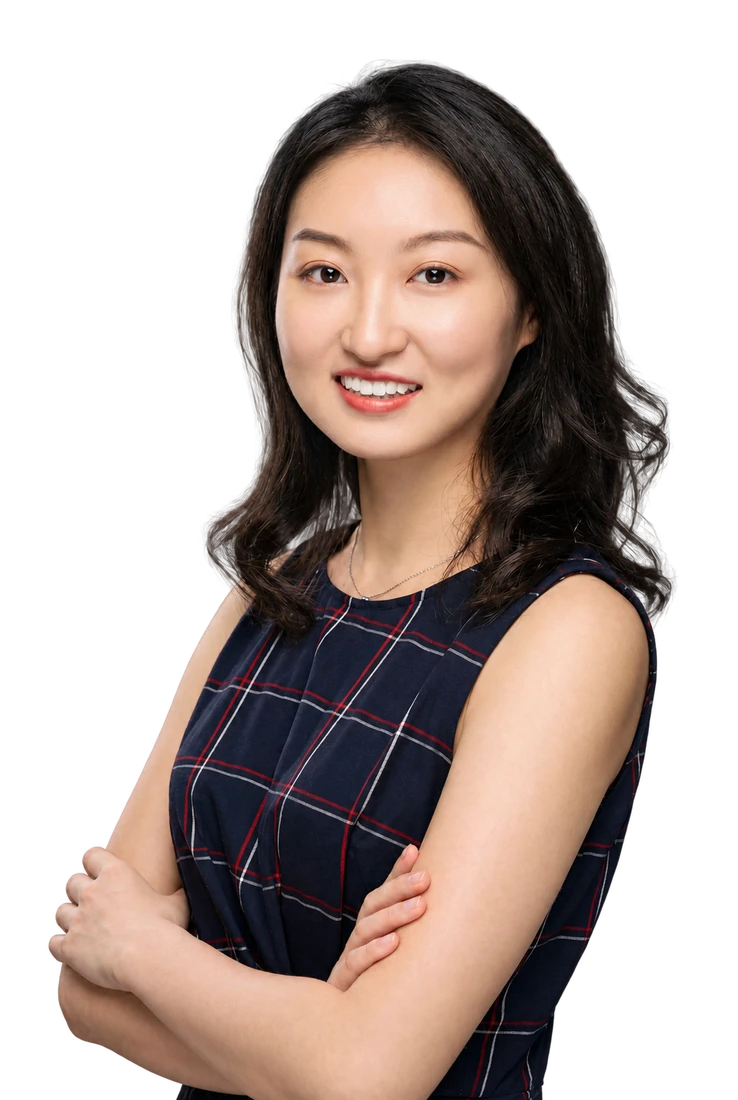
Xintian Wang

Xintian Wang

CPA · Senior Tax Manager

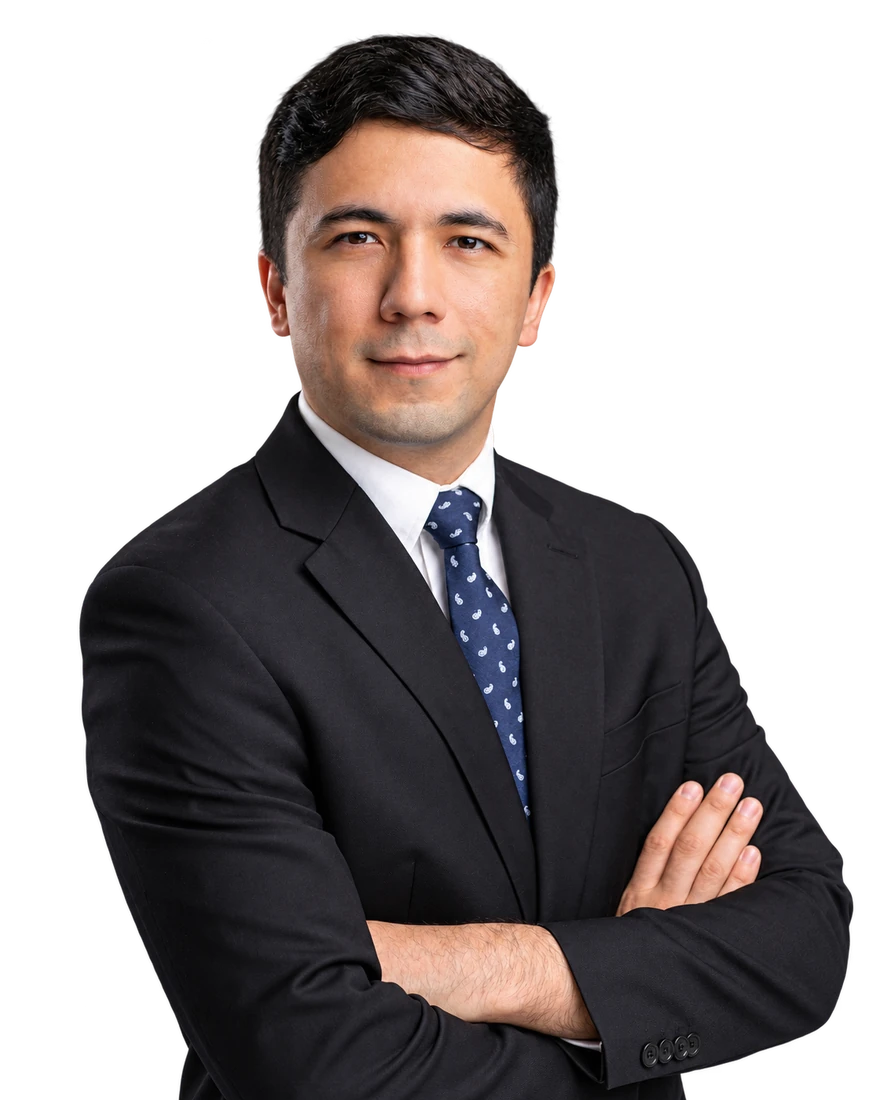
Anvar Akhtamov

Anvar Akhtamov

EA, CPA · Senior Tax Accountant

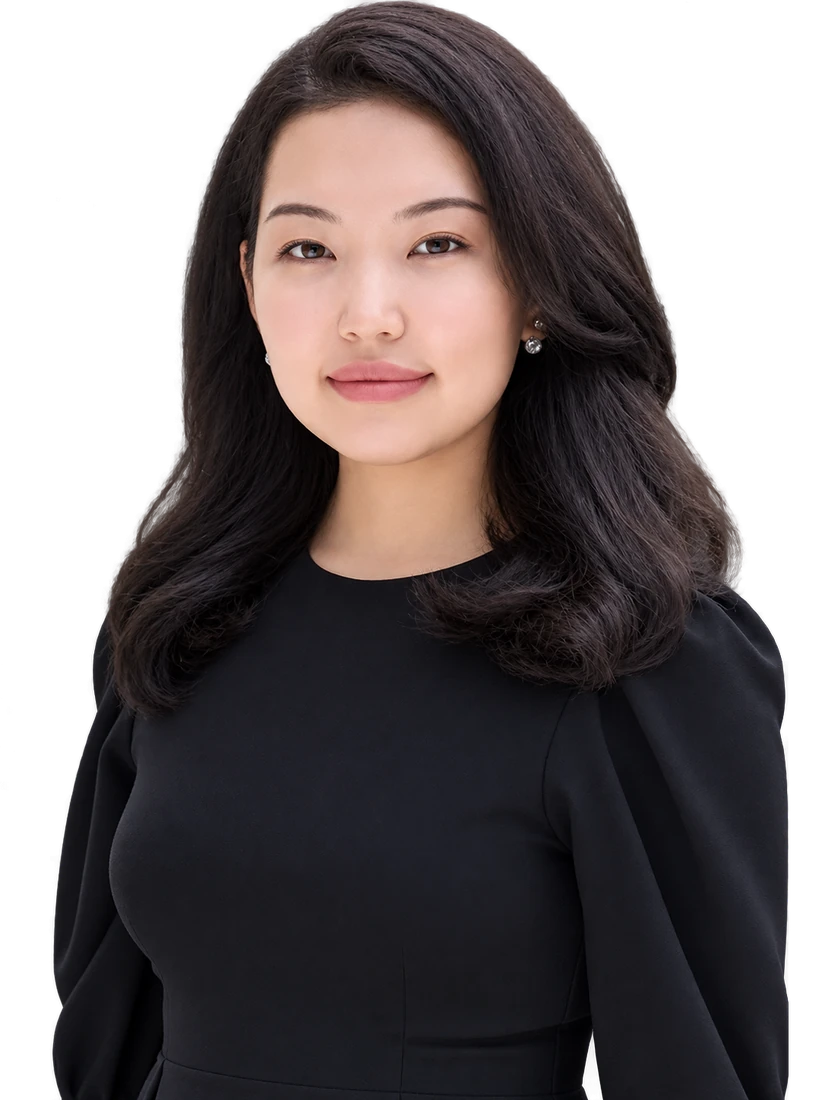
Tsagan Noosan

Tsagan Noosan

EA, CPA

Alexander Chertok

Alexander Chertok

ACCA, DipIFR

Achim von Bodman

Achim von Bodman

CFP

Bobojon Bobojonov

Bobojon Bobojonov

MA

Doniyorkhon Kudratov

Doniyorkhon Kudratov

Tax Accountant

A catch-up deduction.
Can you use it this year?

A valid adjustment and an immediately usable deduction are separate questions. Passive activity, basis, at-risk and other loss limits may affect the outcome.

For short-term rentals, average guest stay and material participation need a review. Real estate professional rules may provide another route in qualifying cases. We assess the facts before projecting current tax savings.

Review the effect on my tax return

Know what the correction costs.

The fee follows the reconstruction and filing work. The size of the potential tax benefit does not set the quote.

Years and records

How many years must be recomputed, and how complete the returns, schedules and acquisition records are.

Properties and ownership

The number of properties, the applicants and entities involved, and the type of change being made.

Study and timing

Whether cost segregation is part of the engagement, the proposed year of change and the return preparation required.

A few questions before you start.

Do I have to amend all the prior returns?

Not for a qualifying accounting method change. Form 3115 can use a Section 481(a) adjustment in the year of change. Other errors may require amended returns or a different procedure.

How far back can the catch-up reach?

The calculation may include cumulative depreciation differences from the property’s earlier years of service. It is not simply limited to the usual amended-return refund window, but the change must qualify under the applicable rules.

Does a one-year error always need Form 3115?

No. A first-year issue may be corrected through an amended return, while some method changes have special rules. We review the actual error and timing before recommending a route.

Can you combine a cost segregation study with the correction?

Yes, where applicable. We scope the study, reconstruction, Form 3115 and return work together so the report and depreciation schedule agree.

Do I need a separate form for every property?

Not necessarily. The applicant and the type of change govern the filing. Some properties can be included together; separate entities or changes may require separate work.

Which bonus depreciation rate applies in a lookback?

The original acquisition and placed-in-service rules, asset eligibility and elections determine the treatment. A later study does not automatically entitle every old asset to today’s rate.

What happens when the property is sold?

Depreciation affects adjusted basis and can create recapture or other tax consequences on sale. We consider holding plans alongside the current adjustment, rather than assuming the deduction is a permanent saving.
Related property tax help.

Find out what your schedule missed.
Start with a review.

Tell us when the property went into service, what was claimed and which years need attention. We’ll identify the records needed and explain the correction work and fee.

★★★★★Over 3000 Reviews

(866) 681-2140
info@dimovtax.com

Request my depreciation review