Get tax and accounting help toll-free on(866) 681-2140

Responsible for an estate or trust?
Get the tax side handled.

Returns you’ve never filed. Beneficiaries waiting. A deadline you’re unsure about. Get an estate and trust tax team to establish what’s due and prepare the work.

01

Tell us what you’re handling

The estate or trust, the assets and any deadline.

02

Know what needs filing

Get the scope, records needed and fee explained.

03

Get the tax work prepared

Returns, beneficiary reporting and accounting coordinated.

Over 3000★★★★★Reviews

You don’t need to know the form.
Start with the situation.

Tell us what you’re responsible for and when it needs attention. We’ll identify the tax work to review.

Talk to us about the estate
The Dimov Tax team

Estate and trust tax services.
Support for the person responsible.

You may be handling these responsibilities for the first time. Our team can take on the tax preparation and explain what we need from you.

Start with the trust or estate documents, available statements and prior returns. If the records need organizing, we can scope the accounting work alongside the filings.

We work with executors, trustees and their attorneys. Your lawyer handles the legal documents and probate issues; we coordinate the tax calculations and reporting.

Explain what my estate needs

Estate tax and income tax.
Two different questions.

An estate can need an income tax return even when no federal estate tax return is required.

Income earned by the estate or trust

Interest, dividends, rents and asset sales can create fiduciary income tax reporting. We review Form 1041, state filings and beneficiary allocations.

The decedent’s final personal return is a separate filing.

Review the income tax returns
The estate’s value and transfers

Form 706 addresses federal estate tax. The filing test depends on the year of death, estate value and relevant lifetime gifts.

A return may also be worth considering to preserve a surviving spouse’s portability election, even where no estate tax is payable.

Discuss estate tax and portability

Before you make a distribution,
understand the tax effect.

Retaining income in a trust or paying it to beneficiaries can produce very different results.

The trust

Income retained

Trust income tax brackets are compressed. Keeping income inside the trust can reach higher rates sooner.

The beneficiary

Income distributed

Qualifying distributions can carry taxable income to beneficiaries, subject to distributable net income and other rules.

The decision

The full picture

The trust document, state law, beneficiary circumstances and cash needs all belong in the review.

Capital gains are often treated differently from ordinary income. We model the allocation rather than assuming every dollar paid out shifts the tax. Timing elections, including the 65-day election where available, need a separate eligibility review.

Review a planned distribution

A filing calendar you can act on.

Tell us the date of death, the tax year and what has already been filed. We check the deadlines that apply to your engagement.

Final Form 1040

Generally due on the normal individual filing deadline in the following year. An unfinished prior-year return may need attention sooner.

Form 1041

Generally due on the 15th day of the fourth month after the tax year ends. Estates can use a fiscal year; trusts generally use a calendar year.

Form 706

Generally due nine months after death when required. Extensions and portability relief have conditions. An extension to file does not automatically extend payment.

Weekend, holiday and special relief rules can affect dates. IRS guidance for executors

From scattered records
to a coordinated filing.

You don’t need a finished spreadsheet to make the first enquiry.

01

Establish the responsibilities

Identify the fiduciary, entity type, tax years, prior filings and immediate deadlines.

02

Organize the records

Review bank and investment statements, property transactions, expenses and beneficiary distributions.

03

Prepare the agreed work

Reconcile the accounting, prepare applicable returns and calculate beneficiary reporting.

04

Review before filing

Walk through the completed work, address questions and confirm the next reporting requirements.

A substantial team. People you can put a name to.

Our team includes CPAs, Enrolled Agents, tax accountants and financial planning specialists. Tell us what the estate or trust needs so we can scope the right tax support.

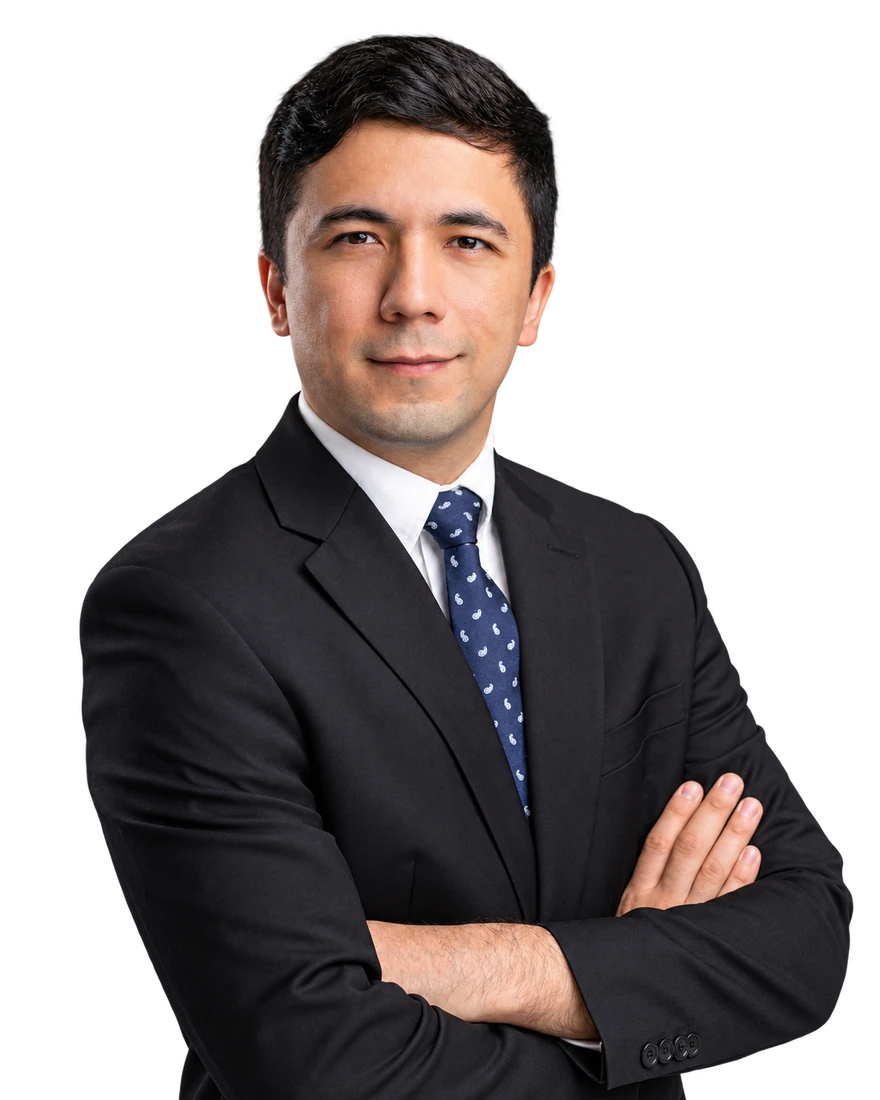
George Dimov

George Dimov

CPA · President

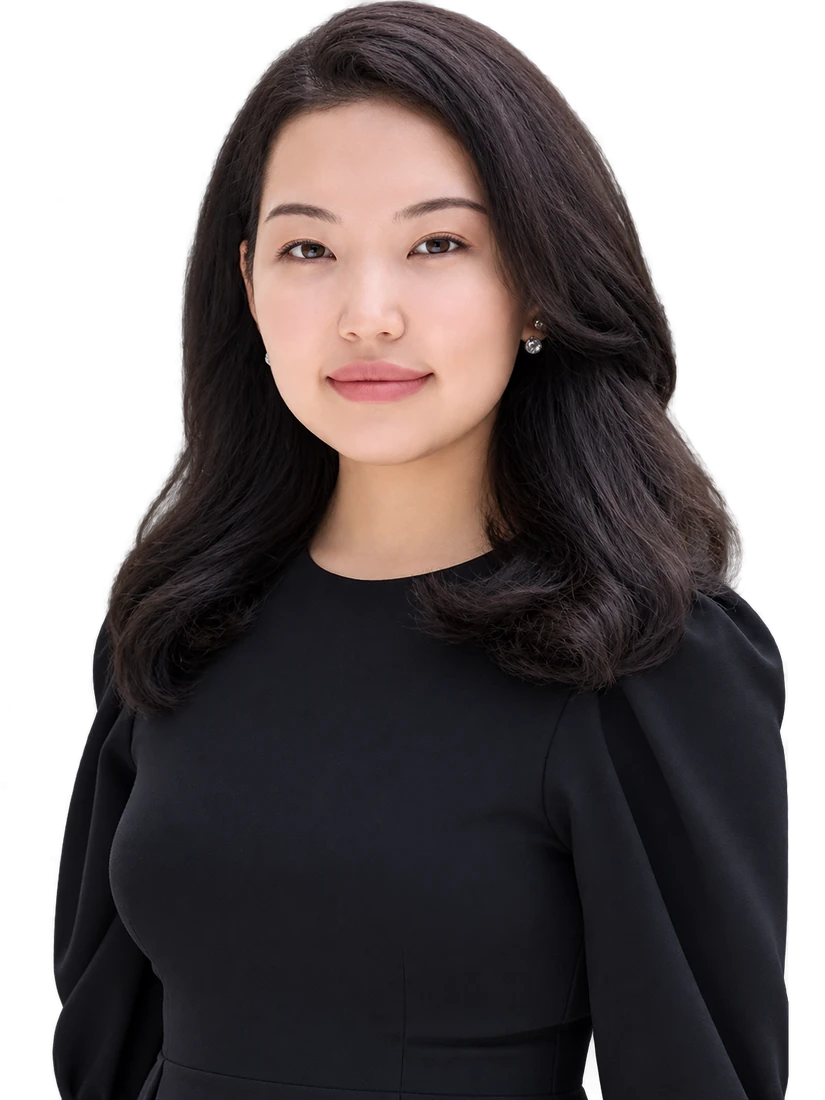
Xintian Wang

Xintian Wang

CPA · Senior Tax Manager

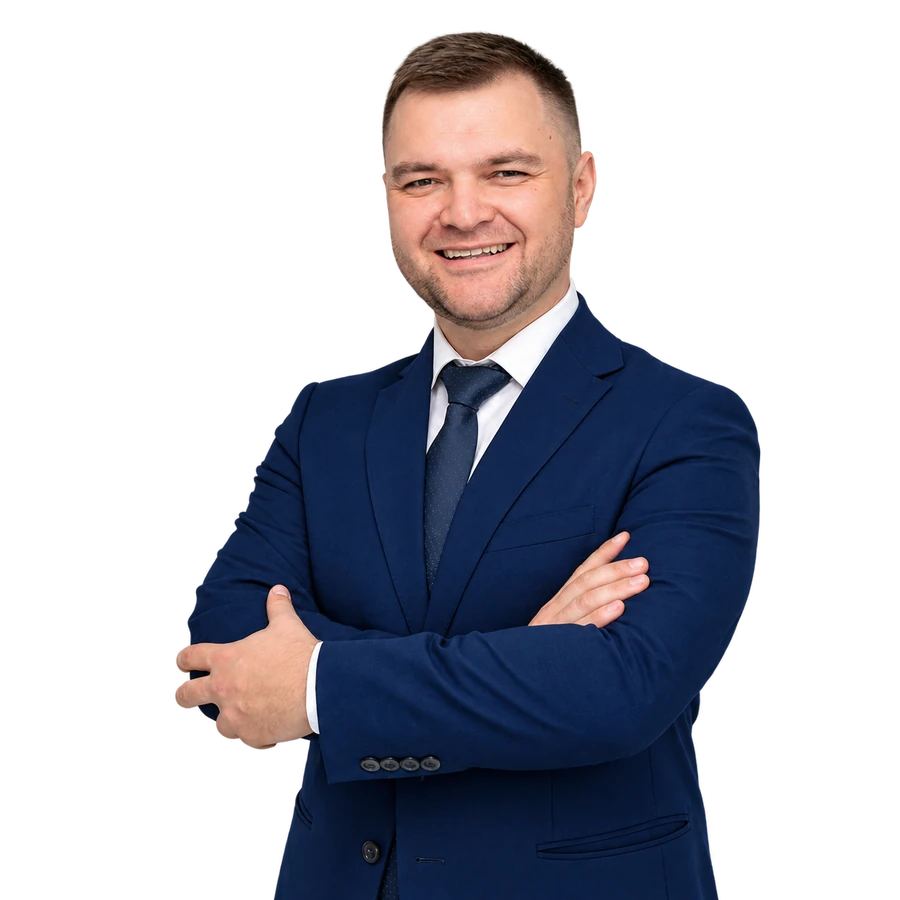
Anvar Akhtamov

Anvar Akhtamov

EA, CPA · Senior Tax Accountant

Tsagan Noosan

Tsagan Noosan

EA, CPA

Alexander Chertok

Alexander Chertok

ACCA, DipIFR

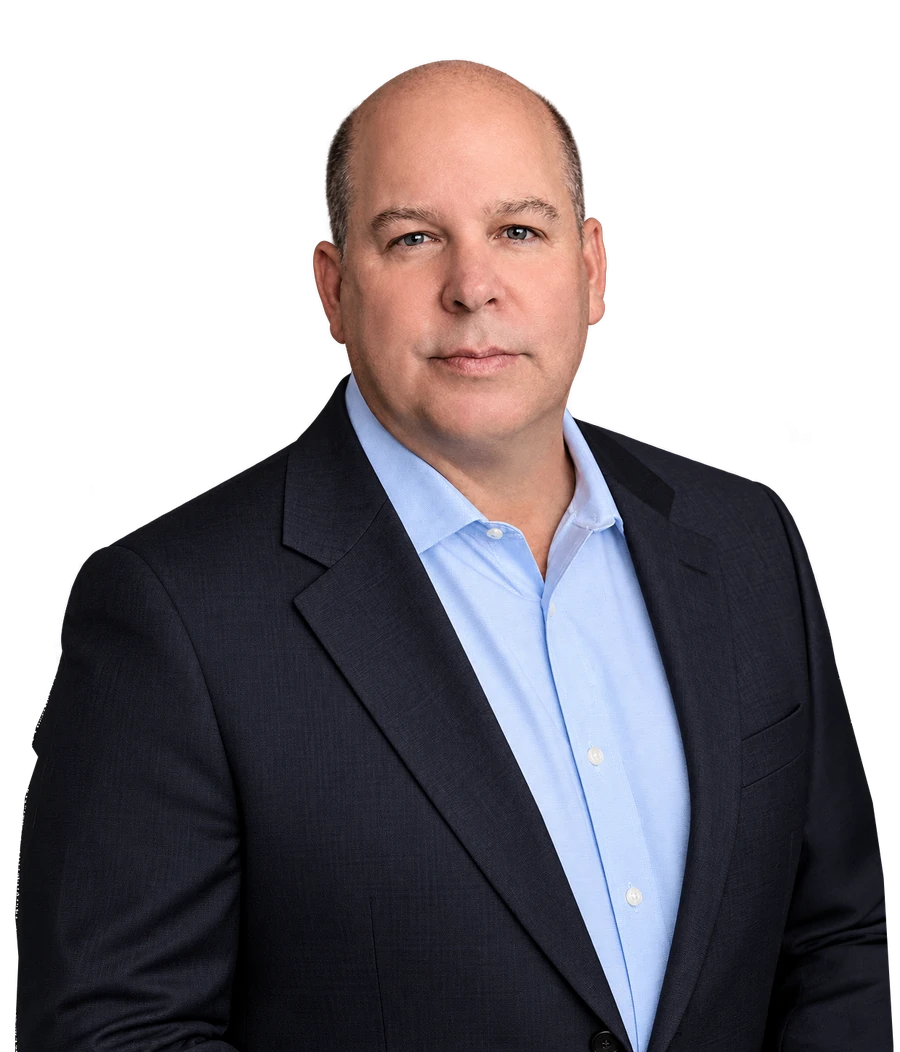
Achim von Bodman

Achim von Bodman

CFP

Bobojon Bobojonov

Bobojon Bobojonov

MA

Doniyorkhon Kudratov

Doniyorkhon Kudratov

Tax Accountant

Property sold. Investments moved.
Make the records match the return.

Inherited assets, brokerage activity and property sales can add another layer to an estate or trust filing.

We review ownership, valuation records, basis, sale proceeds and expenses. The return should reflect the actual transactions, with beneficiary reporting connected to the same figures.

Discuss an asset sale

Know the scope.
Know the fee before work begins.

A straightforward annual trust return and an estate needing reconstructed accounts involve different work.

The filings

Federal and state fiduciary returns, final personal returns, gift tax and estate tax preparation are scoped to the situation.

The activity

Property sales, investment transactions and the number of beneficiaries affect the preparation and allocation work.

The accounting

Rebuilding records is separate work. We explain what needs organizing and include it in the written scope where required.

Request my estate & trust quote

A few questions before you start.

Does every estate need Form 1041?

No. A domestic estate generally files when gross income is at least $600 or it has a nonresident alien beneficiary. Other circumstances can trigger filing. We check the estate’s facts rather than its value alone.

Does every trust file a separate return?

No. Trust classification matters, and grantor trusts can use different reporting methods. A domestic nongrantor trust generally files if it has any taxable income, at least $600 of gross income, or a nonresident alien beneficiary, with additional rules in some cases.

Is receiving an inheritance the same as taxable income?

Generally, the inheritance itself is not federal taxable income. Income generated by inherited assets, certain retirement distributions and income in respect of a decedent can be taxable. A beneficiary K-1 may report income from an estate or trust.

Can you help if the accounting is behind?

Yes. Share the type of records available and the years involved. We can quote record reconstruction and fiduciary accounting separately from return preparation.

Can you work with our attorney?

Yes. We coordinate tax preparation and projections with counsel. Drafting legal documents, interpreting disputed provisions and handling probate litigation remain the attorney’s work.

Should we distribute all the income to reduce tax?

That cannot be answered from the tax rate alone. The governing document, fiduciary duties, beneficiary position, distributable net income and state rules matter. We review the proposed distribution before projecting its effect.

What should I send with the first enquiry?

Tell us whether you are an executor or trustee, the year involved, broadly what assets are held, the number of beneficiaries and any deadline. We can then identify the documents needed and quote the work.

Related estate and trust tax help.

You have enough to handle.
Let’s start with the tax work.

Tell us about the estate or trust, the beneficiaries and any deadline. We’ll explain the records needed, the scope and the fee before preparation begins.

★★★★★Over 3000 Reviews

(866) 681-2140
info@dimovtax.com

Request estate & trust tax help